What is the market overview and industry significance of the Stainless Steel Plate Market?
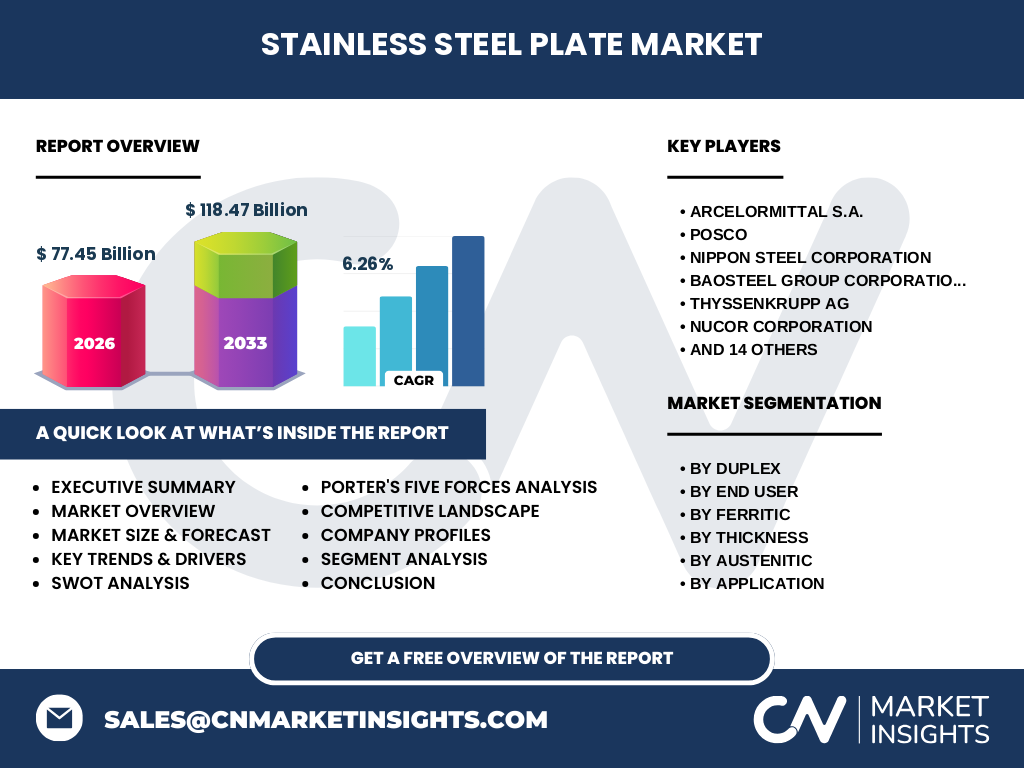
Our analysis indicates that the Stainless Steel Plate Market is valued at $77.45 Billion in 2026. This sector encompasses the production, distribution, and application of corrosion-resistant alloy plates utilized heavily in harsh industrial environments. Corrosion resistance and high tensile strength make these plates indispensable for heavy manufacturing and infrastructure projects globally.
What are the core market drivers, restraints, challenges, and opportunities shaping the Stainless Steel Plate Market?
Growth is propelled by industrial expansion across Asia-Pacific, while strict environmental compliance mandated by regulatory bodies like the EPA creates operational hurdles. Raw material volatility in nickel and chromium acts as a primary restraint. However, rising investments in green energy infrastructure present lucrative opportunities for high-performance alloy suppliers.
Emerging trends and growth patterns in the Stainless Steel Plate Market
The market is witnessing a profound shift toward lightweight, high-strength alloys such as duplex and nitrogen-strengthened grades. Based on our research, fabricators increasingly demand customized plate thicknesses to reduce welding times. This trend favors mills capable of precision rolling and advanced thermal treatment.
How did COVID-19 impact the Stainless Steel Plate Market and shape its recovery trajectory?
Pandemic-induced supply chain bottlenecks and automotive plant shutdowns temporarily depressed demand in 2020. Recovery has been robustly led by stimulus-backed infrastructure spending and a rebound in capital goods manufacturing. The data suggests that producers with diversified regional footprints recovered pre-pandemic output levels significantly faster than localized competitors.
Competitive Benchmarking and Market Concentration in the Stainless Steel Plate Market
The landscape features a mix of consolidated global giants and agile regional producers. Market concentration is moderate-to-high, with industry leaders leveraging economies of scale. Major participants like ArcelorMittal S.A., POSCO, and Nippon Steel Corporation dominate through backward integration and advanced R&D in specialized alloy formulations.
Executive Summary of the Stainless Steel Plate Market
Our comprehensive evaluation highlights a projected market expansion from $77.45 Billion in 2026 to $118.47 Billion by 2033, expanding at a robust 6.26% CAGR. Growth is fundamentally anchored by surging demand across energy, chemical processing, and heavy transport sectors requiring superior metallurgical durability.
Market Forecast and Long-Term Growth Trajectory (2027 to 2033)
The market forecast projects acceleration, driving total valuation from $77.45 Billion up to $118.47 Billion over the 2027 to 2033 forecast period at a 6.26% CAGR. Sustained capital expenditure in offshore wind platforms and chemical refineries will serve as the primary engine for this long-term upward trajectory.
Segmentation Analysis of the Stainless Steel Plate Market
The market segments intricately across product types, thickness grades, and end-user verticals. Key categories include: By Product Type: Austenitic, Ferritic, Martensitic, Duplex, and Other Product Types (Precipitation Hardening, High Manganese, Nitrogen-Strengthened); By Thickness: 3 mm and below, 3 mm to 5 mm, and 5 mm and above; By End User: Construction, Automotive, Machinery, Aerospace, and Other End Users.
Regional Market Analysis and Geographic Distribution
Geographically, demand is heavily skewed toward industrializing economies. Asia-Pacific commands the lion's share of consumption due to massive construction and shipbuilding activities in China, South Korea, and India. Meanwhile, North America and Europe prioritize high-value specialty grades like super duplex for aerospace and stringent chemical processing environments.
In-Depth Regional Review of the Stainless Steel Plate Market
Examining regional nuances reveals that Asian markets excel in high-volume austenitic production, driven by domestic power sector expansion. In contrast, European hubs focus on high-margin, sustainable alloy solutions adhering to strict EU carbon border adjustment mechanisms. Logistical proximity to major ports like Shanghai, Rotterdam, and Houston remains a critical competitive differentiator.
Strategic Company Profiles within the Stainless Steel Plate Market
Industry leaders employ distinct strategies to capture market share. Outokumpu Oyj and Sandvik AB focus on high-performance sustainable stainless solutions, whereas Baosteel Group Corporation and Jindal Stainless Limited leverage massive production capacities to supply cost-competitive plates to global infrastructure projects.
Porter's Five Forces Analysis of Competitive Pressures
Competitive rivalry is intense among tier-one mills, while supplier power remains moderate due to fluctuating raw material costs for nickel and scrap metal. Buyer power is tempered by the specialized nature of high-end grades like 310 series and super duplex. Threat of substitution is low in critical pressure vessel applications.
SWOT Analysis of the Stainless Steel Plate Market
Strengths include exceptional corrosion resistance and recyclability. Weaknesses stem from high initial capital requirements and energy-intensive manufacturing. Opportunities lie in emerging hydrogen energy infrastructure. Threats involve trade tariffs, protectionist policies, and competition from carbon fiber and specialized engineering plastics.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with mining raw inputs like iron ore, chromium, and nickel. Smelting and electric arc furnace melting follow, leading to hot and cold rolling mills operated by giants like ThyssenKrupp AG and Nucor Corporation. Service centers and distributors then process plates before delivery to end-user fabricators.
Investment Insights and High-Potential Areas
Investors should target manufacturers specializing in duplex and nitrogen-strengthened plates, as these grades outpace standard austenitic demand. Companies investing in decarbonized electric arc furnace (EAF) production will likely capture premium pricing from sustainability-conscious clients in the chemical and energy sectors.
Conclusion and Key Takeaways for Market Stakeholders
Reaching $118.47 Billion by 2033 at a 6.26% CAGR, the Stainless Steel Plate Market offers lucrative avenues for strategic participants. Success hinges on mastering advanced metallurgical capabilities, securing stable raw material supply chains, and aligning production portfolios with green energy transition demands.
Research Methodology for Baseline Estimates and Data Triangulation
Our proprietary research methodology triangulates data using a rigorous mix of primary stakeholder interviews with industry executives, comprehensive trade registry data, and secondary macroeconomic indicators. Bottom-up mill production figures are cross-verified with top-down end-user consumption metrics to ensure high accuracy.
Scope of the Report and Coverage Parameters
This report covers global market dynamics for stainless steel plates from 2026 through 2033. It analyzes quantitative shipment volumes and revenue valuations alongside qualitative regulatory assessments. Exclusions include standard stainless steel sheets under 0.5 mm and rebar products, focusing strictly on industrial plate classifications.
Recent Developments in Corporate Strategy and Product Launches
Recent strategic moves emphasize decarbonization and portfolio expansion. Key players like Acerinox S.A. and Aperam SA have increased investments in scrap-based EAF production. Furthermore, strategic acquisitions and joint ventures among firms such as JFE Steel Corporation and Tata Steel Limited aim to secure regional supply dominance.